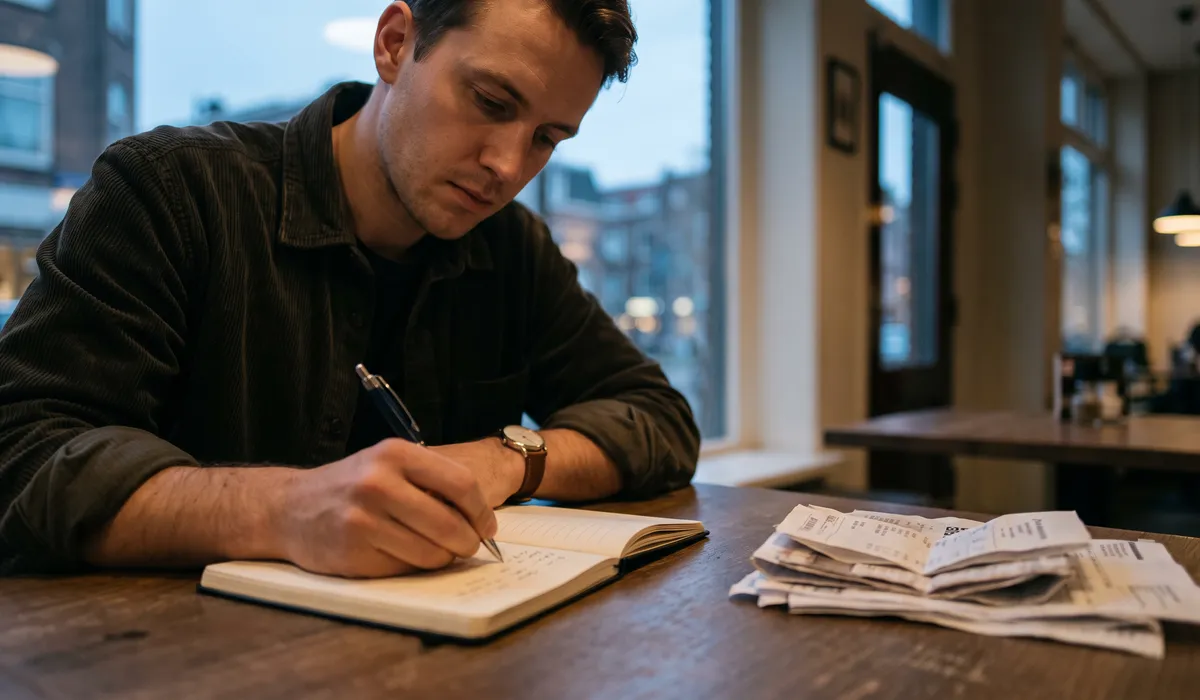
- Budgeting is about understanding how money is being spent and being able to optimize spendings
- The best budget ideas start with setting a goal and tracking expenses every day or week
- To create a budgeting plan you need to know your income, expenses and your target
To stay in control of your finances and improve your financial situation, you need to know what you are spending and how much you're spending. Costs can keep rising, and expenses can fluctuate; that’s why the best budget ideas are the ones that work for your specific case in 2026.
If you’re budgeting to save for a big purchase, retirement, or to build wealth, it’s essential to know how to structure your budget, as smart investors look for the best ways to manage their finances in 2026.
What is budgeting in 2026
In 2026, budgeting isn't about creating a spreadsheet and just noting down expenses; it's about understanding your expenses, setting goals, and managing them more effectively to save. In the Netherlands, integrations between banking apps and budgeting software have made financial oversight easier.
In modern budgeting, a budget should account for inflation, unexpected costs, and income streams such as crypto investments or side hustles. It's about creating an overarching budget based on your income, expenses, and expectations.
Why you need a budget plan in 2026
The reason you need to budget for 2026 is so you won't be left wondering where your money went. It's easy to get sidetracked when salaries are paid, but most people end up with little to spare at the end of the period. Having a solid budget acts as a buffer for uncertainties but also creates opportunities for bigger expenses.
For example, if you have a set budget, you can save a few hundred euros at the end of the month. This means that the amount will increase over time, making it easier to plan for a holiday or a bigger expense, or to start investing. By knowing exactly what your living expenses are, you can determine how much capital is truly available for high-growth opportunities.
Best budgeting methods for beginners
For beginners, the best approach is to stay organized. This means controlling spending, keeping tabs on bills, and saving consistently. First, people should know their take-home income and expenses. Only then can you understand how much flexibility you have.
If you’re keen to budget but you have no experience, below are some examples you can familiarize yourself with:
The 50/30/20 rule
- The 50/30/20 rule divides take-home income into three parts: needs, wants, and investments. This strategy suits beginners, but you can adjust the 50/30/20 split to fit your income and avoid borrowing money at the end of the month.
Zero-based budgeting
- This approach suits beginners because you assign every euro of your income a purpose. Whether it’s investment, food, or accommodation, you set a budget before you receive your salary.
Envelope budgeting
- Similar to the 50/30/20 rule, envelope budgeting separates your salary, and you set yourself limits using cash or digital pots. It helps control variable expenses, but you still have to track how much you’re spending.
Pay yourself first
- The plan means you schedule a payment when you are paid, and you have to live within that budget. It’s a stricter plan and is better suited for people who can’t stick to a budget and keep dipping into their savings.
How to budget in 2026
Creating a budget shouldn't be complicated. For beginners, it's important to break down the process into simple, manageable steps to build a lasting habit.
Define your goal
Every budget starts with a plan. That's the best approach to becoming financially successful. Whether you are aiming to save €10,000 for an emergency fund, set aside €100 each month, or cut expenses, you need to set it.
It's important to be specific. This means setting a date and even an amount for your target. If you want to start investing, the goal should be to invest X amount per month. Clear goals give your budget motivation and a purpose to pursue.
Understand where you start the year
To create an effective budget, you first need to understand your current financial situation. This doesn't require analyzing every single expense from the last few months.
Instead, focus on identifying your largest expenses, your typical daily spending, and the current balance of your savings account. This process will highlight your spending patterns and help you set a realistic budget.
Know your living expenses
This is an important one because living expenses in the Netherlands cost more than just your rent. It includes utilities, food, transportation, and any expenses you've had for at least the past year, such as Netflix or similar.
If you know how much you spend on rent/mortgage, utilities, and public transportation, you can compare that to your salary and see what's left to spend. Living expenses are usually non-negotiable to some extent, so it's important to get them right.
To build a good budget, calculate all expenses for the year and divide by 12 to get a monthly overview.tr
Plan ahead
To budget in 2026, you need to know what expenses are coming your way. Some expenses are recurring, such as income taxes, vacations, or similar larger expenses. To prevent these costs from derailing your plans, set up a monthly budget you save for, so you're not surprised.
Planning ahead means preparing for the unexpected. This includes an emergency fund of a couple of months' salary to help you get by if things go south financially for a period. The emergency fund can range from €1000 to up to six months' salary, depending on what people are comfortable with.
Track expenses
Tracking expenses is where most people fail. For some, using new tracking applications makes budgeting easier; others are used to Google Sheets or similar tools, while some prefer to rely on banking apps to show what they've spent throughout the year.
Why does tracking expenses matter? It's because you get an overview of sub-categories you've spent money on, such as food, entertainment, sports activities, or dining out. Knowing this makes it easier in the future to assess your income and expenses and know where you can save.
Personally, I have a much more detailed tracking process, where I track house expenses, miscellaneous shopping, and even work lunches. I also review my expenses regularly to see if I've gone over budget or stayed within my plan.
Trim where you can
Once you know how much you're spending and where, you can start identifying areas to save. For example, if you're ordering takeout five times a week, consider cutting back to two and cooking at home instead. Small adjustments like this can make a big difference.
The goal of "trimming" expenses is to cut back on some conveniences without making life too difficult. If that means swapping Uber or taxis for public transport, it’s worth considering.
Another key area to watch is unexpected spending on entertainment or shopping. Track your subscriptions and cancel the ones you don’t use. For shopping, try implementing a "24-hour rule" for non-essential purchases to avoid impulse buys.
The takeaway is that small adjustments compound into significant annual savings without changing your lifestyle.
Transform expenses into a budgeting process
Turn your expense tracking into a proactive system. Instead of just recording what you spent, allocate funds at the start of the month.
- The 50/30/20 Rule: A popular method where 50% of income goes to needs, 30% to wants, and 20% to savings and investments.
- Zero-Based Budgeting: Every euro has a job. Income minus expenses (including savings) should equal zero. This ensures no money is left sitting idle.
How to create a monthly savings plan
Creating a budgeting plan is easy in theory but more difficult to implement. To be successful in following through, you have to connect:
- how much you need per month
- at what times of the month you need it
- what your budget actually supports
The budgeting ideas above are general frameworks, but you can adjust them for individual cases. We found that working backward works better than strictly following a pre-set framework.
Here’s how you create your monthly savings plan with each step
Best budget ideas takeaways
Budgeting isn’t about restricting spending. It’s about prioritizing where your money goes so you can take advantage of the other aspects of life. By managing your income, you can redirect funds to grow your wealth through investments. Whether you’re interested in crypto, real estate, investment funds, or building an emergency fund, developing this habit will benefit you in the long run.
Frequently Asked Questions
How to create a monthly budget?
Start by listing your total monthly income. Then subtract your fixed expenses (rent and bills). Next, estimate your variable expenses (groceries, leisure). The remaining amount is your disposable income, which should be allocated toward savings goals.
Can I link my Dutch bank account to budgeting software?
Yes, thanks to PSD2 (Payment Services Directive 2) regulations in Europe, you can securely link your Dutch bank accounts to third-party budgeting apps and software.
About the authors
Written by
Vlad Hategan
SEO content writer
Writes the articles in the Yieldfund knowledge base.
Dutch, English, Romanian
Translated by
Patricia Van den Kerckhove
Senior content translator
Translates and reviews Yieldfund's content in Dutch.
Dutch (NL & BE), French, English